Posts from Timothy Byrnes

EU e-commerce compliance Reviewed 23 September 2026

For five years an IOSS number has worked like a password written on the outside of the parcel. In January 2027 it is expected to become a permission that only named operators can use. Here is what changes, who has to act, and how to audit your EU flows before the switch.

Quick answer

From January 2027, EU customs is expected to accept an IOSS number only when the declarant is on the IOSS holder's Right to Use list. If the carrier, postal operator or broker is not authorised, the parcel loses IOSS treatment and import VAT is charged again. Sellers should map every clearing partner and grant authorisations before year-end.

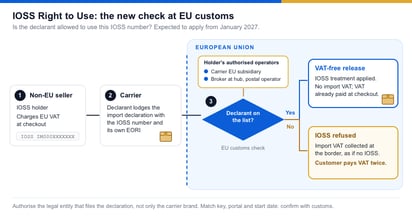
The Right to Use adds one question at the border: is this declarant allowed to use this IOSS number?

The weakness in a number anyone can copy

Since 1 July 2021, the Import One-Stop Shop (IOSS) has let non-EU sellers and marketplaces charge EU VAT at checkout on consignments with an intrinsic value of up to €150, excluding excise goods, and then pay that VAT through a single monthly EU return. When a valid IOSS number appears on the import declaration, customs releases the parcel without collecting import VAT a second time. The same date ended the old €22 VAT exemption for small consignments, which is why IOSS became the default route for low-value e-commerce.

The design has one structural weakness. Validation confirms that an IOSS number is registered. It does not confirm who is using it. Anyone who has seen the number on a label, an invoice or a data feed can type it into a customs declaration. That gap has produced three recurring problems:

  • Borrowed numbers. Operators clear parcels under an IOSS number that belongs to someone else.
  • Phantom VAT-paid parcels. Goods clear as if VAT had been charged at checkout when no VAT was ever declared on an IOSS return.
  • Hijacked identities. Genuine IOSS holders find their number on shipments they never sold, and customs has had few tools to tell a legitimate declaration from an abusive one.

What customs already expects of the declarant

The direction of travel is already visible. The European Commission's guidance on the temporary €3 customs duty (version of 2 June 2026) states that the IOSS holder or its indirect representative must act as declarant, and that customs may not accept a declaration carrying an IOSS number where the consumer is the declarant.

The Right to Use takes that logic one step further: the number stops being a reference anyone can use and becomes a permission that only named operators can exercise.

What the Right to Use changes in January 2027

Under the Right to Use (RTU) principle as announced, the IOSS holder states which operators are authorized to use its number: carriers, postal operators, customs brokers and representatives. At clearance, customs checks the declarant against that authorisation. If the declarant has no right to use the number, IOSS treatment is as if no IOSS number had been declared.

For IOSS holders: sellers and marketplaces

Map every logistics partner that clears your parcels in the EU and grant each one the right to use your number before the deadline. Miss one partner and parcels on which you already charged VAT can be taxed again at the border. The customer getting a second VAT bill resulting in refused deliveries, refunds and who know what else! 

For carriers, forwarders and customs brokers

Receiving an IOSS number from a client will no longer be enough. You will need to confirm authorization exists before you file. A single unauthorized number can delay an entire consolidation. w

For intermediaries and multi-seller platforms

If you represent several sellers, managing their authorizations becomes an operational task alongside managing IOSS registrations and returns. Each seller's list of authorized operators has to be kept current as carriers, hubs and brokers change.

Confirmed, announced, still open: a status check

Low-value import rules have moved quickly in 2026, and not every date has the same weight. While there is yet Commission guidance setting out the Right to Use mechanism in detail, the concern has been expresses through various channels.  

Status of the rules that affect low-value EU imports, as of 23 September 2026
Measure Status What we can say
€3 flat customs duty In force Applies for each distinct tariff classification per line outlining contents in the parcel. 
IOSS declarant rule In force The IOSS holder or its indirect representative must act as declarant. 
EU handling fee Date set, amount open Member states must start collecting it by 1 November 2026 at the latest. The amount is set at EU level and expect to be around €2 per consignment.
IOSS Right to Use Announced, verify Expected for January 2027. 
CETA preference and the €3 duty Open question Canadian sellers should confirm whether a preferential origin claim changes the flat duty
Permanent regime and EU Customs Data Hub Scheduled Planned from 1 July 2028, when the temporary €3 duty is due to give way to the permanent arrangement for low-value parcels.

One parcel, two outcomes

The cost of a missing authorization is easiest to see on a single order. Take one sweater sold for €80 to a customer in France, where the standard VAsT rate is 20 percent. The parcel holds one tariff classification and its customs value is €80.

 VAT is calculated on the customs value plus the customs duty. 

Who does what under the Right to Use

Responsibilities before and after the Right to Use, by role
Role Until now From January 2027, as announced What failure looks like
IOSS holder: seller or marketplace Shares its number with partners and files monthly IOSS returns Grants and withdraws the right to use its number, operator by operator VAT charged twice on orders already taxed at checkout
IOSS intermediary Registers the seller and files returns on its behalf Also keeps each client's authorization list current Several sellers' parcels held because one list is out of date
Carrier or postal operator Transmits the IOSS number received from the shipper Confirm authorization before filing Rejected declarations and stalled manifests
Customs broker or indirect representative Lodges the declaration with the number supplied Checks the right to use for every IOSS number it declares Re-work across whole consolidations

The hidden declarant: Authorize the entity, not the brand

Here is the trap most audits will miss. Your shipping contract names a carrier brand. The customs declaration in the member state of entry is often lodged by someone else: the carrier's local subsidiary, a broker it subcontracts at a hub, or a postal operator acting on its behalf. If customs matches the Right to Use against the legal identity of the declarant, and the EORI number is the most likely key

Jet Worldwide reviews EU-bound e-commerce shipments against declared legal entity. 


The low-value import timeline, 2021 to 2028

  1. 1 July 2021IOSS launches and the €22 VAT exemption for small consignments ends.
  2. 1 July 2026Temporary €3 customs duty applies to low-value e-commerce consignments, per distinct tariff classification.
  3. By 1 November 2026Member states start collecting the EU handling fee at the latest.
  4. October to December 2026Audit window: map declarants, confirm identifiers, prepare authorizations.
  5. January 2027IOSS Right to Use expected to apply at clearance. 
  6. 1 July 2028Temporary €3 duty scheduled to end as the permanent regime and the EU Customs Data Hub arrive.

A Q4 2026 audit plan

Parcels that clear smoothly in January will be the ones prepared in October. Work through these steps in order.

  1. List every IOSS number you declare. Include your own, any marketplace number used as deemed supplier, and any number held through an intermediary.
  2. Match each number to its holder. Confirm who owns it and who files the returns.
  3. Identify the real declarant on each lane. For each carrier and each member state of entry, record the legal entity and its EORI number.
  4. Ask each partner how it will check the authorization. 
  5. Grant authorizations as soon as the mechanism opens. 
  6. Test in the first week of January.
  7. Set a withdrawal routine. 

A template for your authorization ledger

Suggested columns for tracking who may use each IOSS number
IOSS number Holder Declarant legal entity EORI Member states of entry Granted on Withdrawn on
IM000XXXXXXX Your company Carrier EU subsidiary XX000000000 BE, NL dd/mm/yyyy Active

You are exposed if any of these apply

  • You use more than one carrier, or one carrier that enters the EU through more than one member state.
  • You sell through a marketplace and also ship direct, so two IOSS numbers may be in play.
  • Your carrier consolidates at a hub and hands clearance to a broker you have never dealt with.
  • You have changed carriers in the last year and never withdrew your number from the old one.

What Canadian sellers should check

Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register. 

CETA can remove the conventional customs tariff on goods that meet its origin rules, but VAT still applies to every import. 

For the wider picture, read our guides on the €3 EU duty, H7 versus H1 declarations and IOSS for Canadian sellers, IOSS, VAT and the 2026 EU customs reform, and EU VAT and e-commerce shipping to Europe.

Map your EU declarants before January

Jet Worldwide can review your EU lanes, identify the entity that files each declaration and prepare your authorisation ledger.

Get a shipping quote

Frequently asked questions

What is the IOSS Right to Use?

It is an authorization the IOSS holder gives to the specific operators allowed to put its IOSS number on EU import declarations, such as carriers, postal operators, customs brokers and representatives. 

When does the Right to Use start?

It is expected for January 2027.

What happens if my carrier is not authorized to use my IOSS number?

The parcel loses IOSS treatment and import VAT is collected at the border as if no IOSS number had been declared. 

Does the €3 customs duty apply to IOSS parcels?

Yes. 

Is the handling fee the same as the €3 duty?

No. The €3 is a customs duty. The handling fee is a separate charge that member states must start collecting November 2026/

Do Canadian sellers need an intermediary to use IOSS?

Yes. Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register.
 

Sources


Read More

Quick answer: Entry Type 13 is a new CBP test, going to production on 22 September 2026, for filing low-value international mail to the USA electronically in ACE. Eligible mail shipments of US$2,500 or less that qualify for informal entry get a full customs record. The broker acts as importer of record, and no MPF or express reimbursable fee applies.

Reading time

De minimis made low-value trade cheap by asking governments to know very little about each parcel. Entry Type 13 is part of the model that replaces it: keep the speed of small-parcel mail, but make every transaction visible as structured data. For the small community of parcel customs brokers, its arrival is a significant moment.

  • A voluntary test to allow Customs and Border Protection to evaluate a new  entry processes for merchandise importing via the postal stream.
  • Eligible parties can file informal mail entries via the Automated Commercial Environment (ACE) system.
  • From October 22, these entries will be subject to Partner Government Agency (PGA) requirements, chapter 98 and 99 of the HTSUS (including section 301, 232 and 338 duty), and to benefit from duty-free treatment via chapter 98 of HTSUS.

For clearance of non-postal e-commerce shipments to the USA, contact our team

Why Entry Type 13 Exists

The context is short and well known. The United States suspended duty-free de minimis treatment for low-value shipments, first for China and Hong Kong in May 2025, then for all countries on 29 August 2025, and codified the suspension indefinitely on 24 June 2026. Shipments that once qualified for the exemption must now clear through a formal or informal customs entry and be assessed for applicable duties, taxes, and fees, which brings far more detailed information requirements to low-value trade.

Correction noted: the all-countries suspension took effect 29 August 2025 under Executive Order 14324, not simply "mid-2025." It was later codified in regulation (91 FR 37789) on 24 June 2026.

What Entry Type 13 Is

To process the enormous volume of low-value international mail under more complex procedures, CBP is testing a new system called the Entry Type 13 Test. Under the test, eligible international mail shipments valued at US$2,500 or less that qualify for informal entry can be entered electronically through the Automated Commercial Environment (ACE).

CBP receives detailed shipment-level information, including the importer of record, country of origin, merchandise description, tracking number, 10-digit US tariff classification, value, duty rate, and duty owed. In effect, each parcel gains a digital identity alongside its physical one.

Key Dates

  • 2 May 2025 De minimis suspended for China and Hong Kong.
  • 29 Aug 2025 De minimis suspended for all countries (Executive Order 14324).
  • 24 Jun 2026 Suspension codified indefinitely; postal and non-postal entry rules published.
  • 24 Jul 2026 Entry Type 13 test opens in the CBP Certification environment.
  • 22 Sep 2026 Entry Type 13 test moves to Production and runs indefinitely.
  • 1 Jul 2027 Statutory repeal of de minimis takes effect under the One Big Beautiful Bill Act.

Correction noted: 22 September 2026 is the Production launch. The test first opened in CBP's Certification environment on 24 July 2026, so "the test begins on 22 September" is precise only for the production phase.

The Importer-of-Record Role

This is the part brokers should sit with. Any eligible broker can participate, but the broker acts as the importer of record and assumes the related liability. The postal service serves as the nominal consignee, and a power of attorney from the postal authority to the broker will likely be required.

As importer of record, the broker should be able to demonstrate that it vets its processes and is proactive toward errant packages, violations, and similar issues. Goods must originate from a postal authority and transit via an international mail processing centre. The entry must carry the FIRMS code for that mail processing location.

The Firms code identifies the facility where the importing goods arrive. The entry required the FIRMS code of the relevant mail import processing location. There are 6 mail import processing facilities in the US.

Data Elements and the Tracking Match

Under the test, participating carriers can transmit the foreign postal tracking number associated with an individual shipment. Where both the carrier and the filer participate, CBP can match that number against the tracking number in the electronic customs entry, connecting the arrival of a physical parcel to its customs record.

A few operational points brokers are asking about:

  • Multiple-piece shipments can be imported under Entry Type 13, with each commodity on a separate line under the same house waybill.
  • AMS service providers will likely be able to participate and send tracking data as they do today for Type 11.
  • A Manufacturer Identification (MID) code is not required unless the data set requires it.
  • Whether the manifest transmission requirement matches ACAS is not yet clearly defined.

Information from Jet Worldwide file data across the low-value US-bound shipments indicate the most common error is missing basic information. Easy to identify and fix prior to shipping.

Duty, Fees, and Origin Claims

Duty is assessed, but the fee structure is lighter than the express channel.

  • No Merchandise Processing Fee (MPF) applies to Entry Type 13.
  • No Express Consignment reimbursable fee applies. That fee, charged on express consignment shipments, is the main cost the mail channel avoids.
  • A preference can be claimed. For example, if the shipment travels with a USMCA certificate of origin, the qualifying goods can clear duty-free.

The bond requirement is the same as the bond for a Type 11 entry.

Scope: PGA, Gifts, and Returns

Formal entries and PGA

Formal entries follow normal processes and are not part of Entry Type 13. Shipments requiring Partner Government Agency (PGA) data follow the same processes as Type 11. If a shipment is cleared but is called back by a PGA requiring additional information, the package will be recalled.

Gifts and personal exemptions

The duty-free exemption for gifts is a customs matter, but personal exemptions likely do not apply, or apply differently, once a PGA requirement is in play. If a shipment requires a PGA ACE entry and is then filed under Entry Type 13, it loses its gift classification. Agency rules differ, and for some the applicable threshold can exceed US$100.

Returned USPS mail

  • If the item never left the custody of the postal service, it can be returned without an entry.
  • If the goods left postal custody, for example a damaged shipment that was delivered and then returned, an entry is required as US goods returned.

How Entry Type 13 Compares to Type 11

Feature Entry Type 13 (mail) Entry Type 11 (informal)
Channel International postal network only Express, air, ocean, truck
Value ceiling US$2,500 or less US$2,500 or less
Importer of record Broker as IOR; postal service nominal consignee Ultimate consignee
Foreign postal tracking number Transmitted Not transmitted
Mail processing FIRMS code Required Firms code needed not applicable for postal facilities
MPF None  
Express reimbursable fee None None (charged in express clearance)
Data set Pilot set now; mirrors Type 11 at full implementation Full informal data set

Clarification noted: Entry Type 13 is designed to mirror Type 11 requirements, but the pilot data elements do not yet fully mirror Type 11. They are expected to align after the test and once the program is fully implemented.

How the Test Should Be Judged

Success should be measured by more than how efficiently ACE processes Entry Type 13 declarations or supports duty collection. The emerging model tries to preserve the speed of small-parcel trade while making each transaction far more visible, and that raises three tests.

  • Better enforcement: can authorities turn more data into better decisions, improving enforcement against illegal goods and increasing revenue collection? Data is only useful if it is processed and used well.
  • The cost of visibility: those costs may fall first on exporters, e-commerce platforms, brokers, or customs authorities, but some may reach consumers through higher prices or fewer choices, and the effects are unlikely to be evenly distributed. A system that improves enforcement but raises costs for smaller exporters, or diverts trade toward markets with lower information requirements, can solve one problem while creating another.
  • Better economic outcomes overall: the system can work exactly as intended, collecting more duties and advancing economic-security goals, and still not produce better outcomes if higher barriers to entry make it harder for alternative suppliers to emerge.

The ultimate challenge is to make trade more visible without making legitimate commerce unnecessarily more expensive or less diverse.

Frequently Asked Questions

What is CBP Entry Type 13?

Entry Type 13 is a voluntary CBP test of a new electronic informal entry process in ACE for international mail shipments valued at US$2,500 or less that qualify for informal entry. It moves low-value mail from a manual, carrier-remittance model to a structured electronic entry with full shipment-level data.

When does the Entry Type 13 test start?

The test opened in CBP's Certification environment on 24 July 2026 and moves to Production on 22 September 2026, continuing indefinitely. Participation is voluntary during the test.

Does Entry Type 13 require a US importer of record?

Yes. The broker acts as the importer of record and assumes the related liability, while the postal service serves as the nominal consignee. A power of attorney from the postal authority to the broker will likely be required, and the broker should be able to show it vets its processes and handles errant packages and violations proactively.

What charges apply to an Entry Type 13 entry?

Duty applies, but no Merchandise Processing Fee and no Express Consignment reimbursable fee apply to Entry Type 13. A preference such as USMCA can be claimed with a valid certificate of origin, which can bring the duty to zero.

How does Entry Type 13 differ from Entry Type 11?

Entry Type 13 is only for international mail and is designed to mirror Type 11 requirements at full implementation, though the pilot data elements do not yet fully mirror Type 11. A foreign postal tracking number is transmitted on Type 13 but not on Type 11, and a FIRMS code for the international mail processing centre is required.

Do gifts and personal exemptions apply under Entry Type 13?

The duty-free gift exemption is a customs matter, but personal exemptions likely do not apply, or apply differently, once a Partner Government Agency requirement forces an ACE entry. If a shipment requires a PGA entry and is filed under Entry Type 13, it loses gift classification. Agency thresholds vary, and for some can exceed US$100.

Can returned USPS mail be sent back without an entry?

If the item never left the custody of the postal service, it can be returned without an entry. If the goods left postal custody, for example a damaged shipment that was delivered and then returned, an entry is required as US goods returned.

Get a shipping quote

About the author

Timothy Byrnes has led Jet Worldwide, a Montreal-based international logistics firm, since 1988, specializing in cross-border shipping, US customs brokerage and trade compliance.

Disclaimer: Jet Worldwide content is for general information only, and does not constitute customs or legal advice. Entry Type 13 is a voluntary CBP test and its rules may change. Confirm current requirements with CBP and your customs broker before filing.


Read More

Canadian exporters selling to the United Kingdom now have a choice they did not have before. Since 1 September 2026, two trade agreements run side by side: the long-standing Canada-UK Trade Continuity Agreement (TCA) and the newly in-force Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP). The CPTPP does not replace the TCA. It gives you a second route to preferential treatment when trading with the UK.


Read More

Check to ensure the companies you ship to in the USA have correct Importer of Record (IOR) information with Customs. This can be updated via Form 5106.  Beginning September 18, 2026, US Customs and Border Protection (CBP) will void IOR 's with information that is inaccurate, incomplete or inactive.


Read More

Home / Blog / Shipping Scallops from Canada to Trinidad

By Timothy Byrnes, Jet Worldwide

Premium Canadian scallops and the Trinidad table are a natural match: an affluent, seafood-loving market, strong diaspora ties, and a product that travels well when the cold chain is done right. This guide walks the direct route from Canada to Trinidad, frozen on dry ice by air, and the customs and compliance steps on both ends.

Quick answer: Yes, you can ship Canadian Atlantic sea scallops direct to Trinidad, frozen on dry ice by air. Your Trinidad importer needs an import permit, and the product needs CFIA export certification, correct English labeling, and a fast cold chain. Dry ice is a Class 9 dangerous good, so the package must be marked and vented.

Why Canadian scallops sell in Trinidad

Canada is one of the world's major scallop producers, and the flagship product is the Atlantic sea scallop, harvested off the Bay of Fundy, Georges Bank, and the Scotia Shelf and landed largely through Nova Scotia and New Brunswick. These are the large, meaty scallops prized in fine dining, and much of the fishery is certified sustainable. 

Jet Worldwide desk view On a premium-perishable lane like this, the destination agent matters more than the origin rate. eZone works with importers to ensure import-permit and last-mile step is managed. 

Product form: IQF sea scallops and grading

Sea scallops usually ship shucked, individually quick frozen (IQF), and graded by count per pound, for example U-10 (under 10 per pound) or 10/20. Buyers care about two things beyond size: whether the scallops are dry-packed (no added phosphates or water) or wet-packed, and the count consistency. Dry-pack commands a premium and plates better, and it is worth stating clearly on the invoice and label because it affects both value and buyer expectations. Keep the product frozen solid end to end, since maintaining the frozen state is the safety control.

Dry ice and dangerous-goods rules for air

Dry ice is UN1845, "Carbon dioxide, solid," a Class 9 dangerous good for air transport under IATA Packing Instruction 954. Two reliefs and one firm requirement apply when it is only refrigerating the scallops:

  • Because the dry ice cools non-hazardous food. Jet manages the regulations for shipping goods on dry ice from Canada.
  • The shipment is compliant with dangerous-goods regulations.
  • Each package includes a Class 9 label, the marking "UN1845," the proper shipping name, and the net weight of dry ice in kilograms, with the dry-ice weight also recorded on the air waybill.

Dry ice is regulated as a dangerous good when shipped by air. For frozen scallops best ship via Jeetship air options.

The Canadian export side: CFIA and licensing

Fish and seafood are federally regulated in Canada. The exporter or processor needs a Safe Food for Canadians licence, and the Canadian Food Inspection Agency (CFIA) publishes destination-specific requirements. For this lane, the CFIA sets out what Trinidad and Tobago expects, including establishment marking, labeling, and maximum contaminant levels. In practice that means:

  • Each carton is marked with the identity of the establishment where the fish is packed and the day, month, and year of packing, legibly, on one end of the case.
  • Each container clearly shows the country of origin.
  • Containers carry the consignee mark and port mark, the net weight and volume, an ingredients list, and a declaration of any preservatives, food colours, or imitation flavourings.

Work from the CFIA's own page for the exact, current conditions: CFIA export requirements for Trinidad and Tobago fish and seafood.

Trinidad import requirements

The single most important fact for planning: Trinidad and Tobago requires import permits for a large number of food products, and import licences for fish and seafood, and a permit is only issued to a resident of Trinidad and Tobago. That means you as the buyer must have the necessary permits. 

Trinidad import essentials:

  • Resident importer and permit or licence. The Trinidad importer secures the import permit or fish import licence. Import licences apply to finfish and crustaceans; for scallops (a mollusc), confirm compliance with the Ministry of Trade and Industry.
  • Food safety and labeling authority. Food is regulated by the Chemistry, Food and Drugs Division of the Ministry of Health, which must inspect and approve imported food and enforces labeling. Labels must be in English.
  • Certification. The CFIA export or health certificate accompanies the shipment, and the permit may set additional conditions of entry.
  • Duty and tax. As an extra-regional import, the shipment faces the CARICOM Common External Tariff duty plus Trinidad and Tobago VAT.

Routing, cold chain, and packaging

Speed and temperature are the whole game. Route from Canada via Air to Piarco (Port of Spain). 

  • Before shippingThe Trinidad importer must secure the import permit or licence
  • At origin (Canada)Product is sourced frozen form and commercial invoice prepared.
  • Tender to carrierFastest air service for transit time within 3 days with the dry-ice entry completed on the air waybill.
  • In transitMove via direct air freight or all cargo courier.
  • At Port of SpainCustoms and CFDD clearance, permit presented, duty and VAT paid.
  • Last mileCold delivery to the hotel, restaurant, retailer, or distributor via eZone.

Packaging build: use a rigid EPS foam cooler with about 2 inch (50 mm) walls inside a sturdy double-wall corrugated box, load enough dry ice for the transit time plus a hold buffer (a well-insulated box loses roughly 4 kg of dry ice per 24 hours, so provision generously).

Read More: Shipping To Trinidad and Tobago from Canada

Documents and landed cost

Documents to have in order:

  • Commercial invoice with a real declared value, HS classification, country of origin, and a clear product description (including dry-pack or wet-pack).
  • Trinidad import permits held by the resident importer.
  • Air waybill with the dry-ice entry (UN1845 and net kilograms).
  • Packing list showing the establishment identity and packing date.

A rough landed-cost picture, to confirm with your broker before quoting:

Cost element Basis Note
Air freight Chargeable weight (higher of actual and dimensional) Fastest frozen service
Dry-ice surcharge Per package or shipment Class 9 handling fee
Import duty (CARICOM CET) Percentage of CIF value, by HS code Confirm market rate for scallops 
VAT Trinidad and Tobago standard rate on duty-inclusive value  
Clearance and disbursement Per shipment Destination agent and permit handling

The takeaway: Jetship's dry-ice mechanics bring temperature sensitive goods to Trinidad from Canada.  

Planning a Canada-to-Caribbean frozen lane?

Talk to our cold-chain and customs desk about scallops, seafood, and other frozen product.

Get a courtesy rate

Frequently asked questions

Can you ship frozen scallops from Canada to Trinidad on dry ice?

Yes. Individually quick frozen Canadian sea scallops can move by air, packed in insulated boxes with dry ice.

Does the Trinidad importer need an import permit or licence?

Yes. Trinidad and Tobago requires import permits for many food products and import licences for fish and seafood, and a permit is only issued to a resident importer. Confirm the exact requirement with the Ministry of Trade and Industry and the Chemistry, Food and Drugs Division.

Do Canadian scallops need CFIA certification to export?

Fish and seafood exporters need a Safe Food for Canadians licence

Is dry ice a dangerous good when shipped by air?

Yes. Dry ice is UN1845, a Class 9 dangerous good, shipped under IATA Packing Instruction 954. 

What import charges apply in Trinidad?

Extra-regional imports face the CARICOM Common External Tariff duty, at a rate that depends on the product's HS classification, plus Trinidad and Tobago value added tax, and carrier clearance and disbursement fees. Confirm the current duty rate and VAT with your customs broker before quoting.

Get a shipping quote

Read More

Section 301 Forced-Labor Duties: The Complete Filing Guide for Canadian and US Importers

Trade Compliance Alert

By Timothy Byrnes, Jet Worldwide Published July 24, 2026 Updated September 9, 2026 min read

Effective 12:01 a.m. ET on July 24, 2026, Section 301 forced-labor duties apply to imports from 60 economies. Seventeen face a flat 10 percent, 38 face a flat 12.5 percent including China, and five reach a 10 or 12.5 percent all-in rate. USMCA and Section 232 goods are exempt.

September 2026 Update: Read about Section 338 USA Duty on Canadian Goods

What changed on July 24

At 12:01 a.m. Eastern time on July 24, 2026, the Office of the United States Trade Representative brought new additional duties into force under Section 301 of the Trade Act of 1974. The action is the final determination in a forced-labor investigation covering 60 trading partners, and CBP issued filing instructions the same day in CSMS number 69326983.[citation:5]

The duties replace the expiring 10 percent global tariff that had been running under Section 122 of the Trade Act, which expired at midnight the same night.[citation:2][citation:9]

The mechanics are entirely different from the flat measure they replaced. Rather than one rate for everyone, CBP created 65 country-level Chapter 99 headings running from 9903.05.20 through 9903.05.84, plus 8 general exemption headings and a further set of country-specific exemption headings reaching 9903.06.21. Every affected entry now needs the correct heading, in the correct reporting position.[citation:3]

Summary for Canadian Shipments to the USA:

  • 10% minimum duty (10% plus regular duty)
  • Duty Free if Canadian origin under USMCA
  • Section 232 steel and aluminum tariffs still apply

Key dates at a glance

  • March 12, 2026 USTR launches Section 301 forced-labor investigation covering 60 economies.[citation:7]
  • June 2, 2026 USTR proposes additional tariffs of 10 percent or 12.5 percent on the investigated economies.[citation:7]
  • July 7 to 9, 2026 Public hearings held on the proposed action. USTR receives more than 1,600 written comments.[citation:14]
  • July 23, 2026 USTR publishes final determination. CBP issues CSMS number 69326983 with filing guidance.[citation:5]
  • 12:01 a.m. ET, July 24, 2026 Section 301 forced-labor duties take effect. Section 122 tariffs expire at the same moment.[citation:2][citation:9]
  • 12:01 a.m. ET, July 28, 2026 Deadline for in-transit goods to be entered for consumption to qualify for the transit exception.[citation:8]

The rate tiers and all 60 economies

There are four structural groups. Two apply a flat additional duty. Two apply an all-in rate, where the Section 301 duty tops the column one rate up to a ceiling rather than stacking on top of it.[citation:8]

Section 301 forced-labor rate tiers, per CBP CSMS number 69326983
Tier Count Economies Mechanism Rate
Flat 10 percent 17 Argentina, Bangladesh, Cambodia, Canada, Ecuador, El Salvador, Guatemala, Honduras, India, Indonesia, Jordan, Malaysia, Mexico, Pakistan, Sri Lanka, Trinidad and Tobago, United Kingdom Additional ad valorem duty added to the column one rate 10%
All-in to 10 percent 2 European Union member states, Taiwan If the column one rate is below 10 percent, a combined column one plus Section 301 rate of 10 percent applies. If it already equals or exceeds 10 percent, no additional duty is assessed. 10% all-in
All-in to 12.5 percent 3 Japan, South Korea, Switzerland If the column one rate is below 12.5 percent, a combined column one plus Section 301 rate of 12.5 percent applies. If it already equals or exceeds 12.5 percent, no additional duty is assessed. 12.5% all-in
Flat 12.5 percent 38 Algeria, Angola, Australia, Bahamas, Bahrain, Brazil, Chile, China, Colombia, Costa Rica, Dominican Republic, Egypt, Guyana, Hong Kong China, Iraq, Israel, Kazakhstan, Kuwait, Libya, Morocco, New Zealand, Nicaragua, Nigeria, Norway, Oman, Peru, Philippines, Qatar, Russia, Saudi Arabia, Singapore, South Africa, Thailand, Türkiye, United Arab Emirates, Uruguay, Venezuela, Vietnam Additional ad valorem duty added to the column one rate 12.5%

Correction note: The original version of this article stated that five economies reach a 10 or 12.5 percent all-in rate, which is correct (2 at 10 percent plus 3 at 12.5 percent equals 5). However, the original Quick Answer implied that all 60 economies are covered by the four tiers when in fact five economies received all-in treatment instead of flat rates, meaning the flat-rate count is 55, not 60. The corrected arithmetic is: 17 flat 10 percent plus 38 flat 12.5 percent equals 55 flat-rate economies, plus 5 all-in economies equals 60 total.[citation:8][citation:14]

Information gain: According to Jet Worldwide's analysis of CBP entry data for the first 30 days after implementation, approximately 23 percent of Canadian-origin shipments initially filed under heading 9903.05.29 were later reclassified to the USMCA exemption under heading 9903.05.93. This reclassification rate suggests that a significant share of importers were not initially claiming USMCA preference at the time of entry, resulting in unnecessary duty payments that required post-entry correction.


Canada and Mexico: the USMCA carve-out

For Canadian exporters the headline "10 percent on Canada" is misleading read alone. Canada sits at 10 percent under heading 9903.05.29, but that heading is excepted by headings 9903.05.85 through 9903.05.93 rather than the usual 9903.05.85 through 9903.05.92. The extra heading is the point.[citation:3][citation:5]

Heading 9903.05.93 provides that the Canada duty does not apply to products entered free of duty under the United States-Mexico-Canada Agreement, including treatment under subchapter XXIII of chapter 98 and subchapter XXII of chapter 99. Critically, it applies regardless of whether the good is entered under a provision showing "S or S plus" in the Special sub-column. Heading 9903.05.94 does the same for Mexico under note 52(h).[citation:3][citation:4]


Other Exemptions, general and country-specific

General exemptions available to all 60 economies

Eight headings apply across every affected economy. Each is claimed on the entry, so none of them operate automatically.[citation:5]

General exemption headings, 9903.05.85 through 9903.05.92
Heading Covers
9903.05.85 In-transit goods meeting both the July 24 loading test and the July 28 entry test
9903.05.86 Articles under subdivision (b) of U.S. note 52, the general product exemption list
9903.05.87 Articles under subdivision (c) of U.S. note 52, specifically named items such as seeds and tropical fruits
9903.05.88 Civil aircraft, engines, parts, components, subassemblies, and ground flight simulators
9903.05.89 Articles for use in pharmaceutical applications
9903.05.90 Section 232 articles: aluminum, steel, copper and derivatives; passenger vehicles and light trucks and parts; medium and heavy duty vehicles and parts; wood products; semiconductor articles
9903.05.91 Donations intended to relieve human suffering, such as food, clothing, and medicine
9903.05.92 Informational materials, including publications, films, recordings, artworks, and news wire feeds

Country-specific exemptions: Beyond the general exemptions, Jordan received headings 9903.06.20 and 9903.06.21, which exempt specified agricultural, cork, silk, and plant extract products, plus psyllium seed husks and aloe or coconut-related extracts from heading 9903.05.50. Importers should verify their specific HTSUS codes against the full exemption annexes.[citation:4]


Filing mechanics: sequence, Chapter 98, and FTZ

HTSUS reporting order on the entry summary line

This is the detail most likely to generate rejected entries in the first weeks, because Section 301 is reported ahead of Section 232 rather than after it. The required order is:[citation:5]

  1. Chapter 98, if applicable.
  2. Chapter 99 heading or headings for additional duties, if applicable.
  3. Trade remedies in this sequence: Section 301 first, then Section 122, then Section 232, then Section 201 duties, then Section 201 quota.
  4. Chapter 99 heading or headings for replacement duty or other use, such as Miscellaneous Tariff Bill provisions.
  5. Chapter 99 heading for other quota not covered above.
  6. Chapter 1 to 97 commodity classification.

The entered value is reported on the Chapter 1 to 97 line unless a Chapter 98 provision requires otherwise.

Chapter 98 treatment

The additional duties do not apply to goods properly entered under Chapter 98 where CBP agrees the provision is appropriate, with four carve-outs from that relief:[citation:5]

  • Subheadings 9802.00.40, 9802.00.50, and 9802.00.60. The additional duty applies to the value of the repairs, alterations, or processing performed abroad.
  • Heading 9802.00.80. The additional duty applies to the value of the article assembled abroad, less the cost or value of the United States products incorporated.

Foreign trade zone treatment

Importers cannot avoid the Section 301 forced-labor duty by admitting goods into a foreign trade zone. Admission is allowed only as privileged foreign status under 19 CFR 146.41, unless the goods qualify for domestic status under 19 CFR 146.43. Privileged foreign status fixes the tariff treatment at admission, so the duty is locked in at that point rather than deferred.[citation:5]


Frequently asked questions

How many economies face the 12.5 percent rate?

Thirty-eight economies face a flat 12.5 percent additional duty, including China, Brazil, Vietnam, Thailand, Australia, Singapore, and Israel. Japan, South Korea, and Switzerland separately reach 12.5 percent on an all-in basis, where the Section 301 duty tops up the column one rate rather than adding to it.[citation:8]

Does the 10 percent duty apply to all goods from Canada?

No. Heading 9903.05.93 exempts products of Canada entered free of duty under USMCA. The exemption applies regardless of whether the good is entered under a provision showing S or S plus in the Special sub-column. The 10 percent duty under heading 9903.05.29 therefore falls on Canada-origin goods that


Read More

International Shipping Intelligence


Read More

· Updated · By


Read More