EU customs reform · Returns policy · Updated 26 October 2026

Two euros - on tope of three Euro? New import costs to Europe to consider. On a returned item, the fees are not refundable.

Quick answer

From 1 November 2026, the EU charges a €2 Union handling fee per item on online orders shipped to EU consumers from outside the EU, at any order value. Customs keeps the fee when goods are returned, even faulty ones, so sellers must decide before peak whether to absorb it, price it in, or pass it on.

The handling fee is charged at import is not refundable - even if goods are returned. 

What the €2 Union handling fee is...

The Union handling fee is a flat €2 charged on every item in an online order shipped to a consumer in the EU from outside the EU customs territory. The Commission fixed it at €2 in a delegated regulation adopted on 21 September 2026.

The Commission, Irish Revenue and Dutch customs all give 1 November 2026 as the start date.  The Commission will review the amount every two years.

Four facts that decide your cost

  • No value ceiling. The €3 interim customs duty covers only consignments worth €150 or less and expires in July 2028. The €2 fee applies to any order value.
  • Charged per item, not per parcel. One declaration line equals one item. 
  • Not refundable. The fee is not repaid when goods are returned. This applies to faulty goods,  failed deliveries and refused parcels.
  • The fee is not part of the customs value. It does not raise the base for ad valorem duty.

Where it applies

What matters is where the goods are when the customer orders, not where the seller is registered. The fee covers a Canadian merchant shipping direct to France, and European brands that fulfil orders outside the EU. 

Understanding €3 + €2 European Import Fees

Required Product Identifiers Shipments to the EU

Key dates for EU e-commerce charges

  1. Romania applies a national logistics fee of 25 RON per parcel on non-EU B2C shipments under €150.
  2. France applies its national small-parcel tax, €2 per declaration line on non-EU shipments under €150.
  3. The €150 customs duty exemption ends. A €3 interim duty applies per item on consignments of €150 or less.
  4. The recast Union Customs Code, Regulation (EU) 2026/2108, is published.
  5. The Commission sets the Union handling fee at €2 per item.
  6. The €2 Union handling fee applies. EU product identifiers also become mandatory on e-commerce declarations.
  7. Italy's national €2 fee, deferred to align with the EU fee, is due to apply.
  8. The €3 interim duty ends and low-value goods move to normal tariff rates under the EU Customs Data Hub regime. The €2 handling fee continues.

How items are counted

An item a group of goods in one consignment that share the same tariff classification, description and origin and are declared on one line. Dutch customs describes the charge simply as €2 per declaration line. Counting every unit at €2 overstates the cost; counting every parcel at €2 understates it.

Fixed charges before VAT on consignments of €150 or less. Examples adapted from European Commission and Irish Revenue guidance.
Order contents Lines €3 duty €2 fee Total
5 identical T-shirts 1 €3 €2 €5
1 T-shirt and 1 belt 2 €6 €4 €10
3 T-shirts and 1 watch 2 €6 €4 €10
Pen, notebook and key ring worth €10 3 €9 €6 €15

The last row is the one to remember: €15 of fixed charges on €10 of goods. Because classification, description and origin all have to match, two near-identical products split across different subheadings, or the same product sourced from two countries, become two lines and two fees. Cleaning up your HS codes and origin data before November is the cheapest saving available.

What a fully returned order costs

A UK retailer ships a €60 order to a customer in Germany: a jumper and a pair of trousers, which fall under two tariff classifications. From November 2026 that order carries €6 in duty and €4 in handling fees, so €10 in fixed charges before VAT. The customer sends both items back.

Returned order · UK to Germany

Goods, 2 tariff lines €60.00
Customs duty, 2 × €3 €6.00
Union handling fee, 2 × €2 €4.00
Fixed charges before VAT €10.00
Refunded to customer €60.00 plus standard delivery
Handling fee kept by customs €4.00
€3 duty kept (goods not faulty) €6.00
Unrecoverable if the seller paid €10.00

VAT refund treatment is separate and not shown.

The duty is usually lost too. Irish Revenue - for example -says the €3 duty is refunded only when the goods are faulty. Consignments over €150 are different: they pay normal tariff duty, which Irish Revenue says may be refunded if the goods are returned within 90 days.Who pays the €2 depends on how you ship


The fee is best paid by the online seller transparently shown to the consumer at checkout. 

Jet's Delivered Duty Paid (DDP)

  • Import clearance, usually through IOSS for consignments of €150 or less.
  • The €2 is sellers cost: absorb it or build it into prices.
  • The customer sees one price and surprise costs on delivery.
  • On a return, the unrecoverable charges need to be accounted for.

Delivered at Place (DAP)

  • Clearance usually falls to the customer through the courier.
  • The courier collects duty and the fee before handover.
  • The customer paid the courier, not you.
  • Refused parcels still lose the fee, and someone pays for the trip back.

What the customer is owed after a return

Article 13 of the EU Consumer Rights Directive (Directive 2011/83/EU) requires a trader to refund every payment received from a customer who withdraws from an online purchase within the 14-day withdrawal period, including the standard delivery charge. The refund is due without undue delay and no later than 14 days after the trader is told of the withdrawal, although the trader may hold it until the goods arrive back or the customer shows proof of sending them, whichever comes first.

That creates the €2 problem. If you add the fee as its own line at checkout, ask your legal adviser whether it counts as one of those payments. If it does, you refund the €2 to the shopper and cannot recover it from customs, so you pay it twice in effect.

Return postage follows a different rule. Under Article 14 of the Directive, and as the EU's Your Europe guidance puts it, you can ask shoppers to pay the direct cost of returning goods after a change of mind, provided you told them before they bought. Returning faulty goods is at your cost. Itemize every refund message: goods, delivery and any return postage deducted. The customer should be able to follow their refund without understanding customs. Campaigns start earlier every year. IMRG's review of Black Friday 2025 found that 60% of retailers in its panel launched earlier than in 2024, so EU return terms need to be live before the first promotion, not after the first complaint.


What this means if you ship from Canada

From our Montreal team: A most common misreading is that CETA solves this. It does not. CETA preference can reduce or remove customs duty on Canadian-origin goods, but the handling fee is not a duty, so a qualifying product shipped direct to an EU consumer still pays €2 per item. 

The structural alternative is to hold stock inside the EU.  Contact our team for a consultation: info@jetworldwide.ca.

Jet Worldwide data point. For Canadian sellers, the line count, not the parcel count, is the number to budget against.

Related: the €3 EU customs duty explained and EU product identifiers from 1 November.

Frequently asked questions

Is the €2 handling fee refunded when an item is returned?

No. Customs keeps the €2 once the import declaration is accepted, including for faulty goods. 

Can sellers pass the handling fee on to customers?

Yes. If you show it as a separate checkout line, confirm with your legal adviser whether you must refund it when a customer cancels.

Is the fee charged per parcel or per item?

Per item, which in practice means per declaration line. Goods in one consignment that share a tariff classification, description and origin count as one item, so five identical T-shirts cost €2 while a T-shirt and a belt cost €4.

Does the handling fee apply to orders over €150?

Yes. The €2 handling fee applies to e-commerce goods shipped to EU consumers at any value.

Does CETA remove the €2 fee on Canadian-origin goods?

No. CETA preference affects customs duty, and the handling fee is not a duty. 

Is the handling fee part of the customs value?

No. Dutch customs states that the handling fee is not part of the customs value, so it does not increase the base on which ad valorem duty is calculated.

Get a shipping quote

Related guides


Timothy Byrnes
Timothy Byrnes has led Jet Worldwide, a Montreal-based international logistics firm, since 1988, specializing in cross-border shipping and trade compliance.


Read More

EU e-commerce compliance Reviewed 23 September 2026

For five years an IOSS number has worked like a password written on the outside of the parcel. In January 2027 it is expected to become a permission that only named operators can use. Here is what changes, who has to act, and how to audit your EU flows before the switch.

Quick answer

From January 2027, EU customs is expected to accept an IOSS number only when the declarant is on the IOSS holder's Right to Use list. If the carrier, postal operator or broker is not authorised, the parcel loses IOSS treatment and import VAT is charged again. Sellers should map every clearing partner and grant authorisations before year-end.

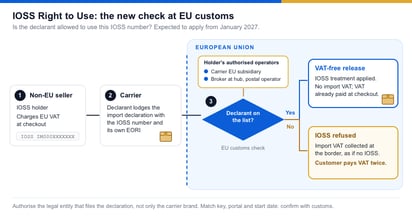
The Right to Use adds one question at the border: is this declarant allowed to use this IOSS number?

The weakness in a number anyone can copy

Since 1 July 2021, the Import One-Stop Shop (IOSS) has let non-EU sellers and marketplaces charge EU VAT at checkout on consignments with an intrinsic value of up to €150, excluding excise goods, and then pay that VAT through a single monthly EU return. When a valid IOSS number appears on the import declaration, customs releases the parcel without collecting import VAT a second time. The same date ended the old €22 VAT exemption for small consignments, which is why IOSS became the default route for low-value e-commerce.

The design has one structural weakness. Validation confirms that an IOSS number is registered. It does not confirm who is using it. Anyone who has seen the number on a label, an invoice or a data feed can type it into a customs declaration. That gap has produced three recurring problems:

  • Borrowed numbers. Operators clear parcels under an IOSS number that belongs to someone else.
  • Phantom VAT-paid parcels. Goods clear as if VAT had been charged at checkout when no VAT was ever declared on an IOSS return.
  • Hijacked identities. Genuine IOSS holders find their number on shipments they never sold, and customs has had few tools to tell a legitimate declaration from an abusive one.

What customs already expects of the declarant

The direction of travel is already visible. The European Commission's guidance on the temporary €3 customs duty (version of 2 June 2026) states that the IOSS holder or its indirect representative must act as declarant, and that customs may not accept a declaration carrying an IOSS number where the consumer is the declarant.

The Right to Use takes that logic one step further: the number stops being a reference anyone can use and becomes a permission that only named operators can exercise.

What the Right to Use changes in January 2027

Under the Right to Use (RTU) principle as announced, the IOSS holder states which operators are authorized to use its number: carriers, postal operators, customs brokers and representatives. At clearance, customs checks the declarant against that authorisation. If the declarant has no right to use the number, IOSS treatment is as if no IOSS number had been declared.

For IOSS holders: sellers and marketplaces

Map every logistics partner that clears your parcels in the EU and grant each one the right to use your number before the deadline. Miss one partner and parcels on which you already charged VAT can be taxed again at the border. The customer getting a second VAT bill resulting in refused deliveries, refunds and who know what else! 

For carriers, forwarders and customs brokers

Receiving an IOSS number from a client will no longer be enough. You will need to confirm authorization exists before you file. A single unauthorized number can delay an entire consolidation. w

For intermediaries and multi-seller platforms

If you represent several sellers, managing their authorizations becomes an operational task alongside managing IOSS registrations and returns. Each seller's list of authorized operators has to be kept current as carriers, hubs and brokers change.

Confirmed, announced, still open: a status check

Low-value import rules have moved quickly in 2026, and not every date has the same weight. While there is yet Commission guidance setting out the Right to Use mechanism in detail, the concern has been expresses through various channels.  

Status of the rules that affect low-value EU imports, as of 23 September 2026
Measure Status What we can say
€3 flat customs duty In force Applies for each distinct tariff classification per line outlining contents in the parcel. 
IOSS declarant rule In force The IOSS holder or its indirect representative must act as declarant. 
EU handling fee Date set, amount open Member states must start collecting it by 1 November 2026 at the latest. The amount is set at EU level and expect to be around €2 per consignment.
IOSS Right to Use Announced, verify Expected for January 2027. 
CETA preference and the €3 duty Open question Canadian sellers should confirm whether a preferential origin claim changes the flat duty
Permanent regime and EU Customs Data Hub Scheduled Planned from 1 July 2028, when the temporary €3 duty is due to give way to the permanent arrangement for low-value parcels.

One parcel, two outcomes

The cost of a missing authorization is easiest to see on a single order. Take one sweater sold for €80 to a customer in France, where the standard VAsT rate is 20 percent. The parcel holds one tariff classification and its customs value is €80.

 VAT is calculated on the customs value plus the customs duty. 

Who does what under the Right to Use

Responsibilities before and after the Right to Use, by role
Role Until now From January 2027, as announced What failure looks like
IOSS holder: seller or marketplace Shares its number with partners and files monthly IOSS returns Grants and withdraws the right to use its number, operator by operator VAT charged twice on orders already taxed at checkout
IOSS intermediary Registers the seller and files returns on its behalf Also keeps each client's authorization list current Several sellers' parcels held because one list is out of date
Carrier or postal operator Transmits the IOSS number received from the shipper Confirm authorization before filing Rejected declarations and stalled manifests
Customs broker or indirect representative Lodges the declaration with the number supplied Checks the right to use for every IOSS number it declares Re-work across whole consolidations

The hidden declarant: Authorize the entity, not the brand

Here is the trap most audits will miss. Your shipping contract names a carrier brand. The customs declaration in the member state of entry is often lodged by someone else: the carrier's local subsidiary, a broker it subcontracts at a hub, or a postal operator acting on its behalf. If customs matches the Right to Use against the legal identity of the declarant, and the EORI number is the most likely key

Jet Worldwide reviews EU-bound e-commerce shipments against declared legal entity. 


The low-value import timeline, 2021 to 2028

  1. 1 July 2021IOSS launches and the €22 VAT exemption for small consignments ends.
  2. 1 July 2026Temporary €3 customs duty applies to low-value e-commerce consignments, per distinct tariff classification.
  3. By 1 November 2026Member states start collecting the EU handling fee at the latest.
  4. October to December 2026Audit window: map declarants, confirm identifiers, prepare authorizations.
  5. January 2027IOSS Right to Use expected to apply at clearance. 
  6. 1 July 2028Temporary €3 duty scheduled to end as the permanent regime and the EU Customs Data Hub arrive.

A Q4 2026 audit plan

Parcels that clear smoothly in January will be the ones prepared in October. Work through these steps in order.

  1. List every IOSS number you declare. Include your own, any marketplace number used as deemed supplier, and any number held through an intermediary.
  2. Match each number to its holder. Confirm who owns it and who files the returns.
  3. Identify the real declarant on each lane. For each carrier and each member state of entry, record the legal entity and its EORI number.
  4. Ask each partner how it will check the authorization. 
  5. Grant authorizations as soon as the mechanism opens. 
  6. Test in the first week of January.
  7. Set a withdrawal routine. 

A template for your authorization ledger

Suggested columns for tracking who may use each IOSS number
IOSS number Holder Declarant legal entity EORI Member states of entry Granted on Withdrawn on
IM000XXXXXXX Your company Carrier EU subsidiary XX000000000 BE, NL dd/mm/yyyy Active

You are exposed if any of these apply

  • You use more than one carrier, or one carrier that enters the EU through more than one member state.
  • You sell through a marketplace and also ship direct, so two IOSS numbers may be in play.
  • Your carrier consolidates at a hub and hands clearance to a broker you have never dealt with.
  • You have changed carriers in the last year and never withdrew your number from the old one.

What Canadian sellers should check

Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register. 

CETA can remove the conventional customs tariff on goods that meet its origin rules, but VAT still applies to every import. 

For the wider picture, read our guides on the €3 EU duty, H7 versus H1 declarations and IOSS for Canadian sellers, IOSS, VAT and the 2026 EU customs reform, and EU VAT and e-commerce shipping to Europe.

Map your EU declarants before January

Jet Worldwide can review your EU lanes, identify the entity that files each declaration and prepare your authorisation ledger.

Get a shipping quote

Frequently asked questions

What is the IOSS Right to Use?

It is an authorization the IOSS holder gives to the specific operators allowed to put its IOSS number on EU import declarations, such as carriers, postal operators, customs brokers and representatives. 

When does the Right to Use start?

It is expected for January 2027.

What happens if my carrier is not authorized to use my IOSS number?

The parcel loses IOSS treatment and import VAT is collected at the border as if no IOSS number had been declared. 

Does the €3 customs duty apply to IOSS parcels?

Yes. 

Is the handling fee the same as the €3 duty?

No. The €3 is a customs duty. The handling fee is a separate charge that member states must start collecting November 2026/

Do Canadian sellers need an intermediary to use IOSS?

Yes. Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register.


Sources


Read More