EU e-commerce compliance Reviewed 23 September 2026
For five years an IOSS number has worked like a password written on the outside of the parcel. In January 2027 it is expected to become a permission that only named operators can use. Here is what changes, who has to act, and how to audit your EU flows before the switch.
Quick answer
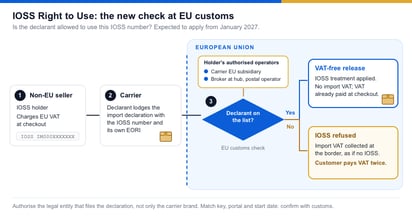
From January 2027, EU customs is expected to accept an IOSS number only when the declarant is on the IOSS holder's Right to Use list. If the carrier, postal operator or broker is not authorised, the parcel loses IOSS treatment and import VAT is charged again. Sellers should map every clearing partner and grant authorisations before year-end.
The weakness in a number anyone can copy
Since 1 July 2021, the Import One-Stop Shop (IOSS) has let non-EU sellers and marketplaces charge EU VAT at checkout on consignments with an intrinsic value of up to €150, excluding excise goods, and then pay that VAT through a single monthly EU return. When a valid IOSS number appears on the import declaration, customs releases the parcel without collecting import VAT a second time. The same date ended the old €22 VAT exemption for small consignments, which is why IOSS became the default route for low-value e-commerce.
The design has one structural weakness. Validation confirms that an IOSS number is registered. It does not confirm who is using it. Anyone who has seen the number on a label, an invoice or a data feed can type it into a customs declaration. That gap has produced three recurring problems:
- Borrowed numbers. Operators clear parcels under an IOSS number that belongs to someone else.
- Phantom VAT-paid parcels. Goods clear as if VAT had been charged at checkout when no VAT was ever declared on an IOSS return.
- Hijacked identities. Genuine IOSS holders find their number on shipments they never sold, and customs has had few tools to tell a legitimate declaration from an abusive one.
What customs already expects of the declarant
The direction of travel is already visible. The European Commission's guidance on the temporary €3 customs duty (version of 2 June 2026) states that the IOSS holder or its indirect representative must act as declarant, and that customs may not accept a declaration carrying an IOSS number where the consumer is the declarant.
The Right to Use takes that logic one step further: the number stops being a reference anyone can use and becomes a permission that only named operators can exercise.
What the Right to Use changes in January 2027
Under the Right to Use (RTU) principle as announced, the IOSS holder states which operators are authorized to use its number: carriers, postal operators, customs brokers and representatives. At clearance, customs checks the declarant against that authorisation. If the declarant has no right to use the number, IOSS treatment is as if no IOSS number had been declared.
For IOSS holders: sellers and marketplaces
Map every logistics partner that clears your parcels in the EU and grant each one the right to use your number before the deadline. Miss one partner and parcels on which you already charged VAT can be taxed again at the border. The customer getting a second VAT bill resulting in refused deliveries, refunds and who know what else!
For carriers, forwarders and customs brokers
Receiving an IOSS number from a client will no longer be enough. You will need to confirm authorization exists before you file. A single unauthorized number can delay an entire consolidation. w
For intermediaries and multi-seller platforms
If you represent several sellers, managing their authorizations becomes an operational task alongside managing IOSS registrations and returns. Each seller's list of authorized operators has to be kept current as carriers, hubs and brokers change.
Confirmed, announced, still open: a status check
Low-value import rules have moved quickly in 2026, and not every date has the same weight. While there is yet Commission guidance setting out the Right to Use mechanism in detail, the concern has been expresses through various channels.
| Measure | Status | What we can say |
|---|---|---|
| €3 flat customs duty | In force | Applies for each distinct tariff classification per line outlining contents in the parcel. |
| IOSS declarant rule | In force | The IOSS holder or its indirect representative must act as declarant. |
| EU handling fee | Date set, amount open | Member states must start collecting it by 1 November 2026 at the latest. The amount is set at EU level and expect to be around €2 per consignment. |
| IOSS Right to Use | Announced, verify | Expected for January 2027. |
| CETA preference and the €3 duty | Open question | Canadian sellers should confirm whether a preferential origin claim changes the flat duty |
| Permanent regime and EU Customs Data Hub | Scheduled | Planned from 1 July 2028, when the temporary €3 duty is due to give way to the permanent arrangement for low-value parcels. |
One parcel, two outcomes
The cost of a missing authorization is easiest to see on a single order. Take one sweater sold for €80 to a customer in France, where the standard VAsT rate is 20 percent. The parcel holds one tariff classification and its customs value is €80.
VAT is calculated on the customs value plus the customs duty.
Who does what under the Right to Use
| Role | Until now | From January 2027, as announced | What failure looks like |
|---|---|---|---|
| IOSS holder: seller or marketplace | Shares its number with partners and files monthly IOSS returns | Grants and withdraws the right to use its number, operator by operator | VAT charged twice on orders already taxed at checkout |
| IOSS intermediary | Registers the seller and files returns on its behalf | Also keeps each client's authorization list current | Several sellers' parcels held because one list is out of date |
| Carrier or postal operator | Transmits the IOSS number received from the shipper | Confirm authorization before filing | Rejected declarations and stalled manifests |
| Customs broker or indirect representative | Lodges the declaration with the number supplied | Checks the right to use for every IOSS number it declares | Re-work across whole consolidations |
The hidden declarant: Authorize the entity, not the brand
Here is the trap most audits will miss. Your shipping contract names a carrier brand. The customs declaration in the member state of entry is often lodged by someone else: the carrier's local subsidiary, a broker it subcontracts at a hub, or a postal operator acting on its behalf. If customs matches the Right to Use against the legal identity of the declarant, and the EORI number is the most likely key
Jet Worldwide reviews EU-bound e-commerce shipments against declared legal entity.
The low-value import timeline, 2021 to 2028
- 1 July 2021IOSS launches and the €22 VAT exemption for small consignments ends.
- 1 July 2026Temporary €3 customs duty applies to low-value e-commerce consignments, per distinct tariff classification.
- By 1 November 2026Member states start collecting the EU handling fee at the latest.
- October to December 2026Audit window: map declarants, confirm identifiers, prepare authorizations.
- January 2027IOSS Right to Use expected to apply at clearance.
- 1 July 2028Temporary €3 duty scheduled to end as the permanent regime and the EU Customs Data Hub arrive.
A Q4 2026 audit plan
Parcels that clear smoothly in January will be the ones prepared in October. Work through these steps in order.
- List every IOSS number you declare. Include your own, any marketplace number used as deemed supplier, and any number held through an intermediary.
- Match each number to its holder. Confirm who owns it and who files the returns.
- Identify the real declarant on each lane. For each carrier and each member state of entry, record the legal entity and its EORI number.
- Ask each partner how it will check the authorization.
- Grant authorizations as soon as the mechanism opens.
- Test in the first week of January.
- Set a withdrawal routine.
A template for your authorization ledger
| IOSS number | Holder | Declarant legal entity | EORI | Member states of entry | Granted on | Withdrawn on |
|---|---|---|---|---|---|---|
| IM000XXXXXXX | Your company | Carrier EU subsidiary | XX000000000 | BE, NL | dd/mm/yyyy | Active |
You are exposed if any of these apply
- You use more than one carrier, or one carrier that enters the EU through more than one member state.
- You sell through a marketplace and also ship direct, so two IOSS numbers may be in play.
- Your carrier consolidates at a hub and hands clearance to a broker you have never dealt with.
- You have changed carriers in the last year and never withdrew your number from the old one.
What Canadian sellers should check
Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register.
CETA can remove the conventional customs tariff on goods that meet its origin rules, but VAT still applies to every import.
For the wider picture, read our guides on the €3 EU duty, H7 versus H1 declarations and IOSS for Canadian sellers, IOSS, VAT and the 2026 EU customs reform, and EU VAT and e-commerce shipping to Europe.
Map your EU declarants before January
Jet Worldwide can review your EU lanes, identify the entity that files each declaration and prepare your authorisation ledger.

Frequently asked questions
What is the IOSS Right to Use?
It is an authorization the IOSS holder gives to the specific operators allowed to put its IOSS number on EU import declarations, such as carriers, postal operators, customs brokers and representatives.
When does the Right to Use start?
It is expected for January 2027.
Does the €3 customs duty apply to IOSS parcels?
Yes.
Is the handling fee the same as the €3 duty?
No. The €3 is a customs duty. The handling fee is a separate charge that member states must start collecting November 2026/
Do Canadian sellers need an intermediary to use IOSS?
Yes. Canada has no VAT mutual-assistance agreement with the EU, so a Canadian seller must appoint an EU-established IOSS intermediary to register.